Strategic advisory · Indonesia

Science. Strategy.
Optimization.

Turning complex business challenges into optimal decisions.

We help organizations make better strategic and operational decisions through Operations Research, Decision Science, and Advanced Analytics.

Our expertise

From insight to impact.

Scientific approaches to complex business problems, grounded in the decisions that matter.

Strategic Decision Optimization

Compare choices and their trade-offs.
Business & Operational Optimization

Align resources with business priorities.

Investment & Financial Optimization

Understand returns, cash flow, and risk.

Forecasting & Predictive Analytics

Explore demand and future uncertainty.

Network & Resource Optimization

Consider how capacity can be allocated.

Decision Support Systems

Bring relevant information into focus.
Illustration of a modern real estate development by a lake
Property & real estate

Scientific intelligence for better real estate decisions.

From development and investment to sales and management, we apply analytical thinking to the decisions shaping real estate value.

  • Development & Land Optimization
  • Investment & Asset Management
  • Sales & Marketing Optimization
  • Property Management
  • Brokerage & Network Optimization
Explore the Perspective
Industries

One analytical perspective.
Multiple applications.

Optimization principles can illuminate choices across a wide range of business environments.
City skyline

Real Estate & Property

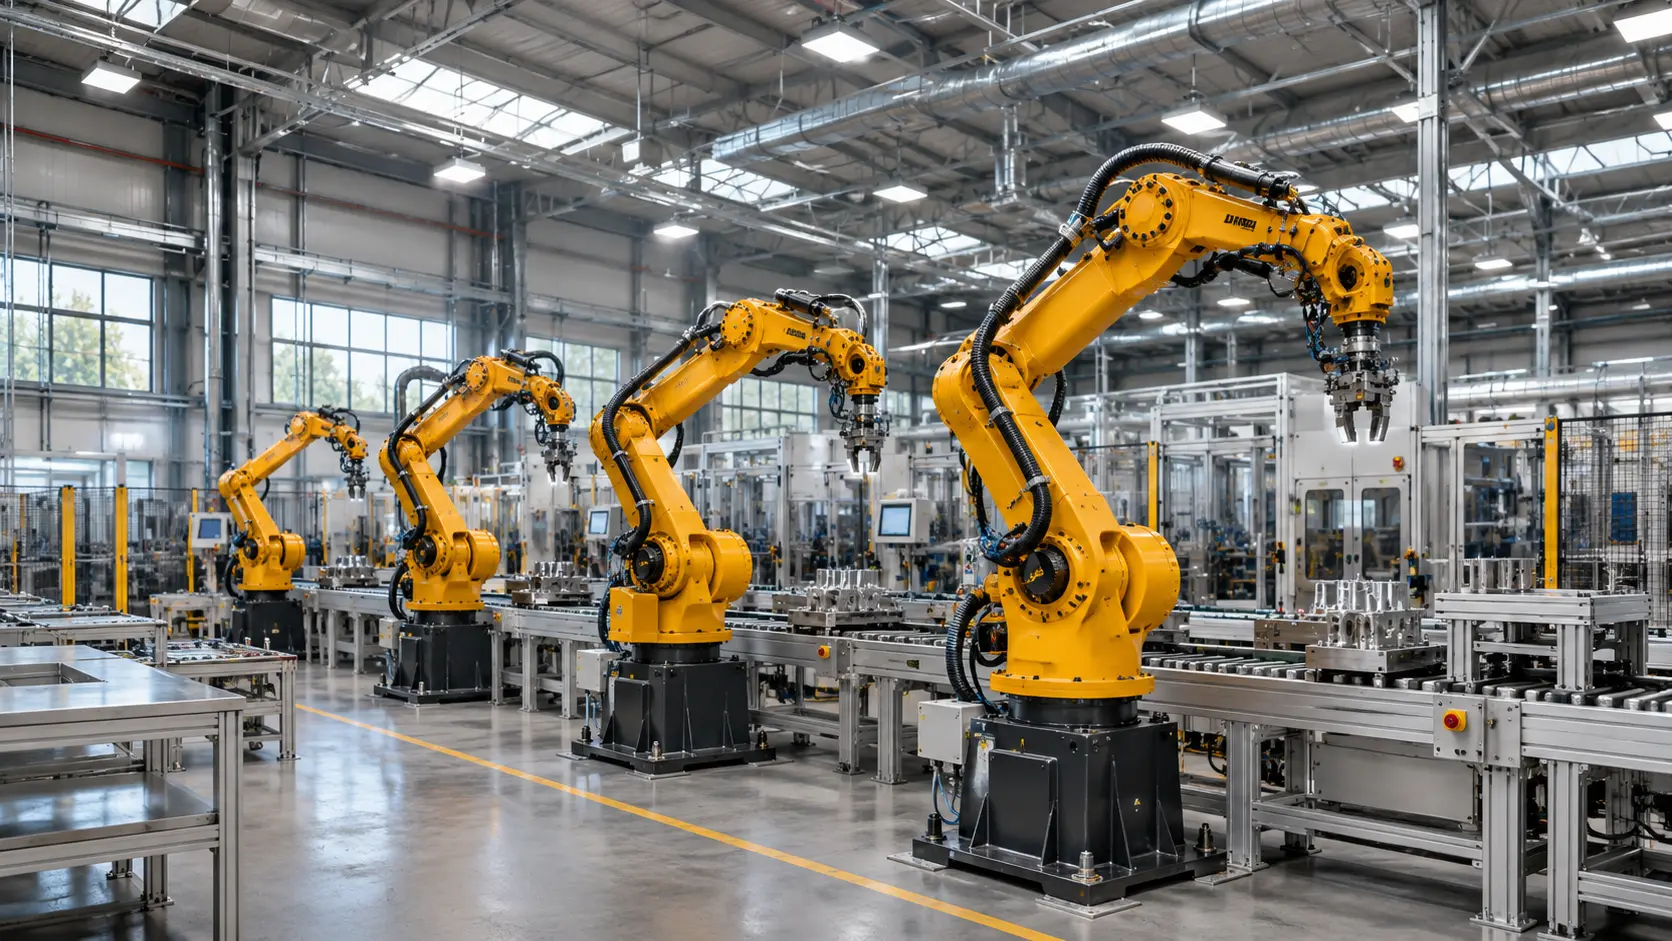
Automated manufacturing facility

Manufacturing & Industrial

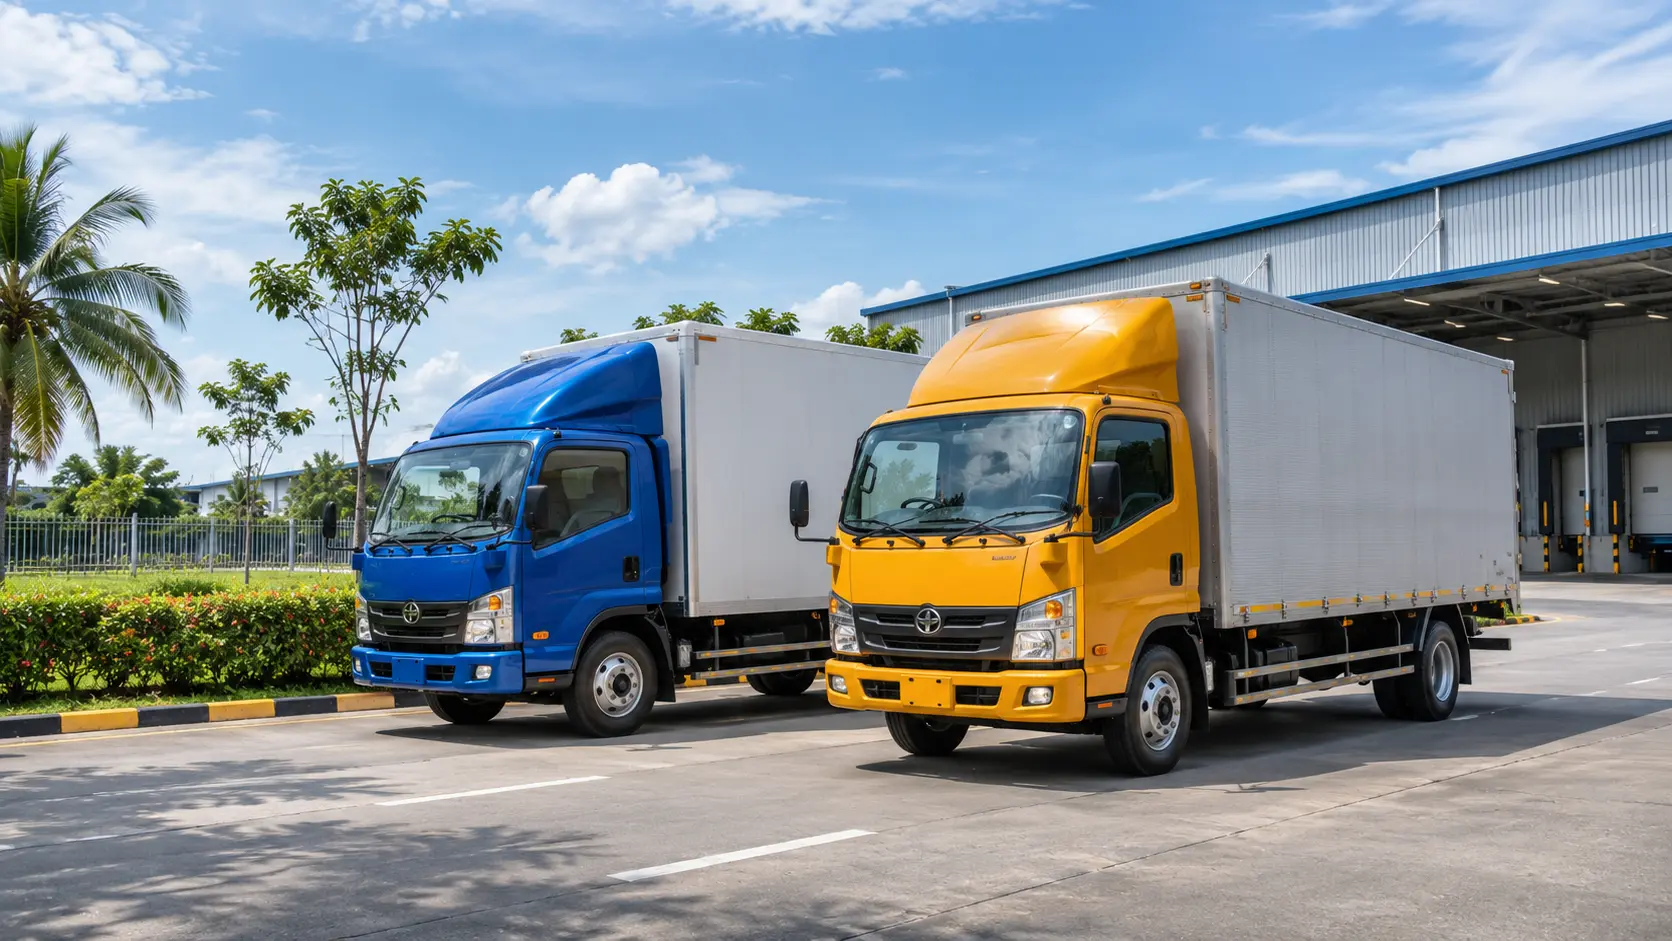
Logistics trucks

Logistics & Supply Chain

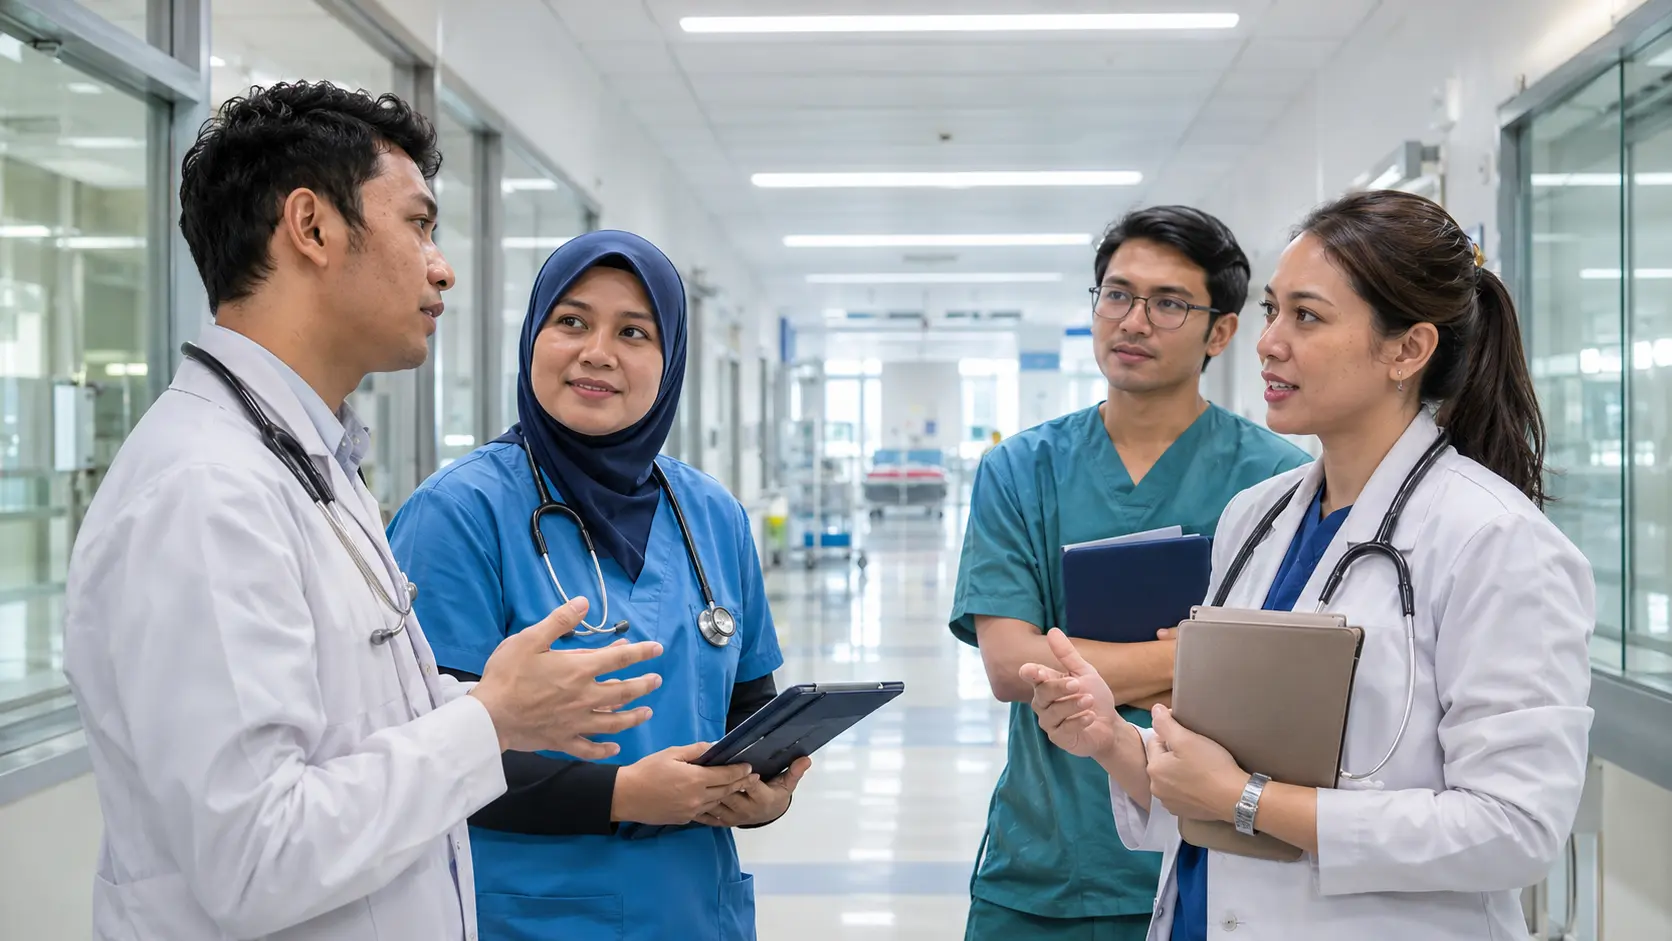
Healthcare professionals

Healthcare

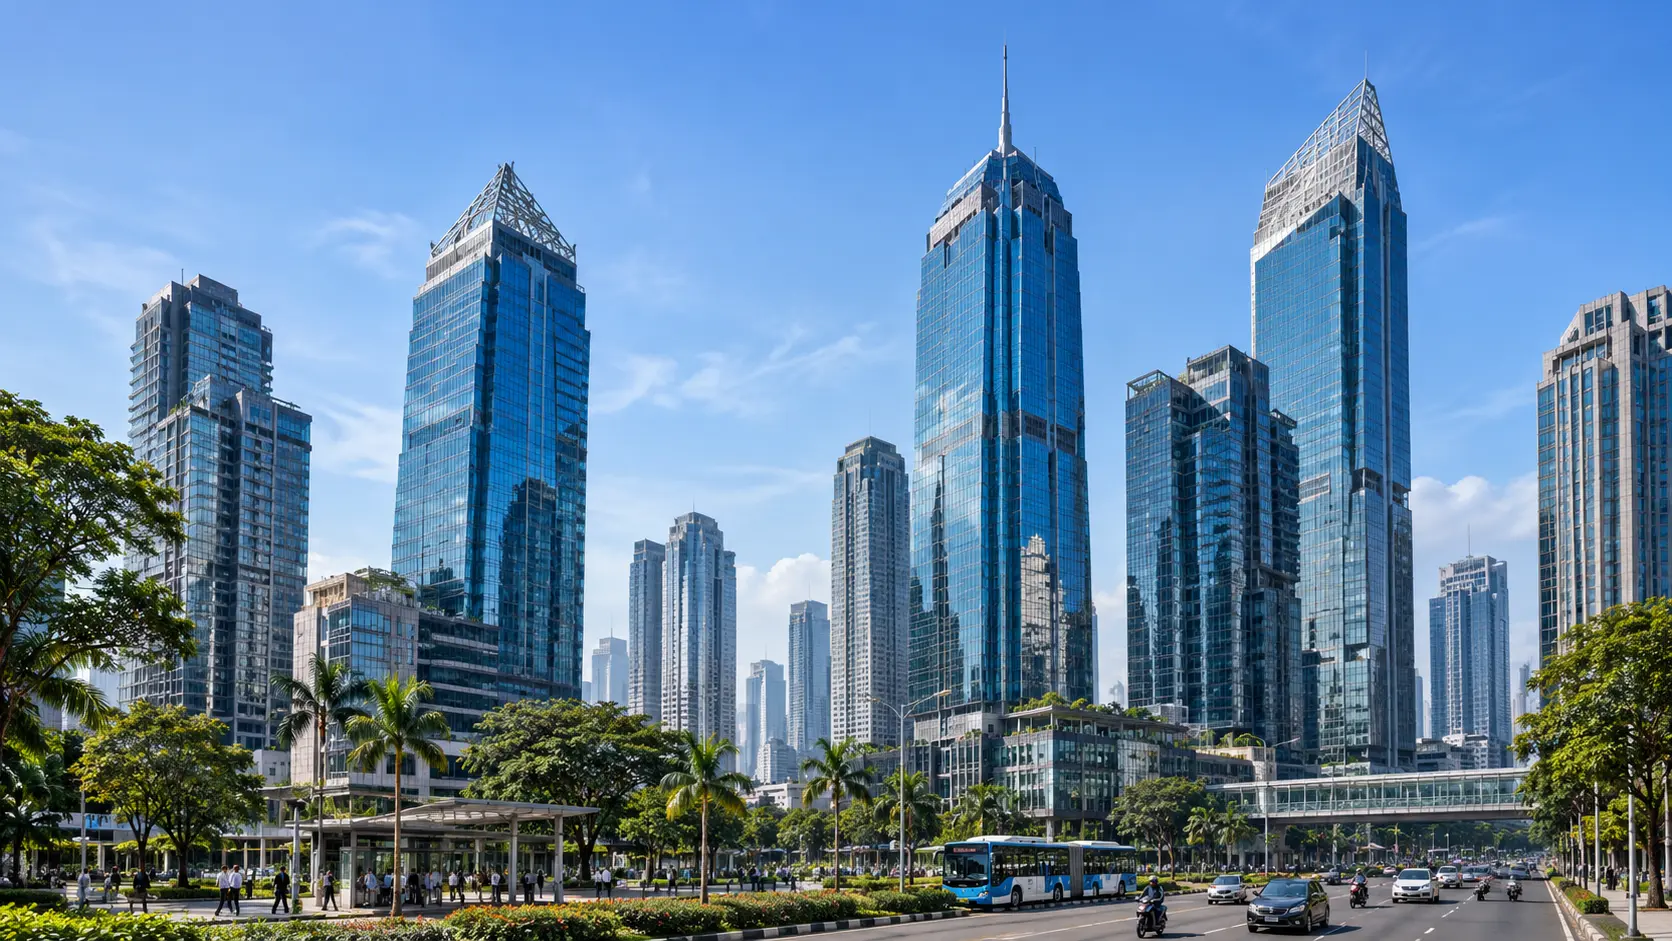
Financial district skyline

Financial Services

Retail interior

Retail & Distribution

HENTZ’s principal focus is real estate. The other sectors shown illustrate potential applications of optimization.

A different perspective

A strong plan is prepared for other possibilities.

A single projection cannot capture every possible outcome. Understanding what might change helps you evaluate your options more thoughtfully.

What if...

Cash flow may not arrive as planned.

When sales slow, funding needs and development timelines may change. The question: do spending plans and development phases still make sense?

Illustrative business questions only; not a forecast or project calculation.

Insights

Ideas. Analysis. Perspectives.

Explore perspectives on Operations Research, real estate, and strategic decision-making.
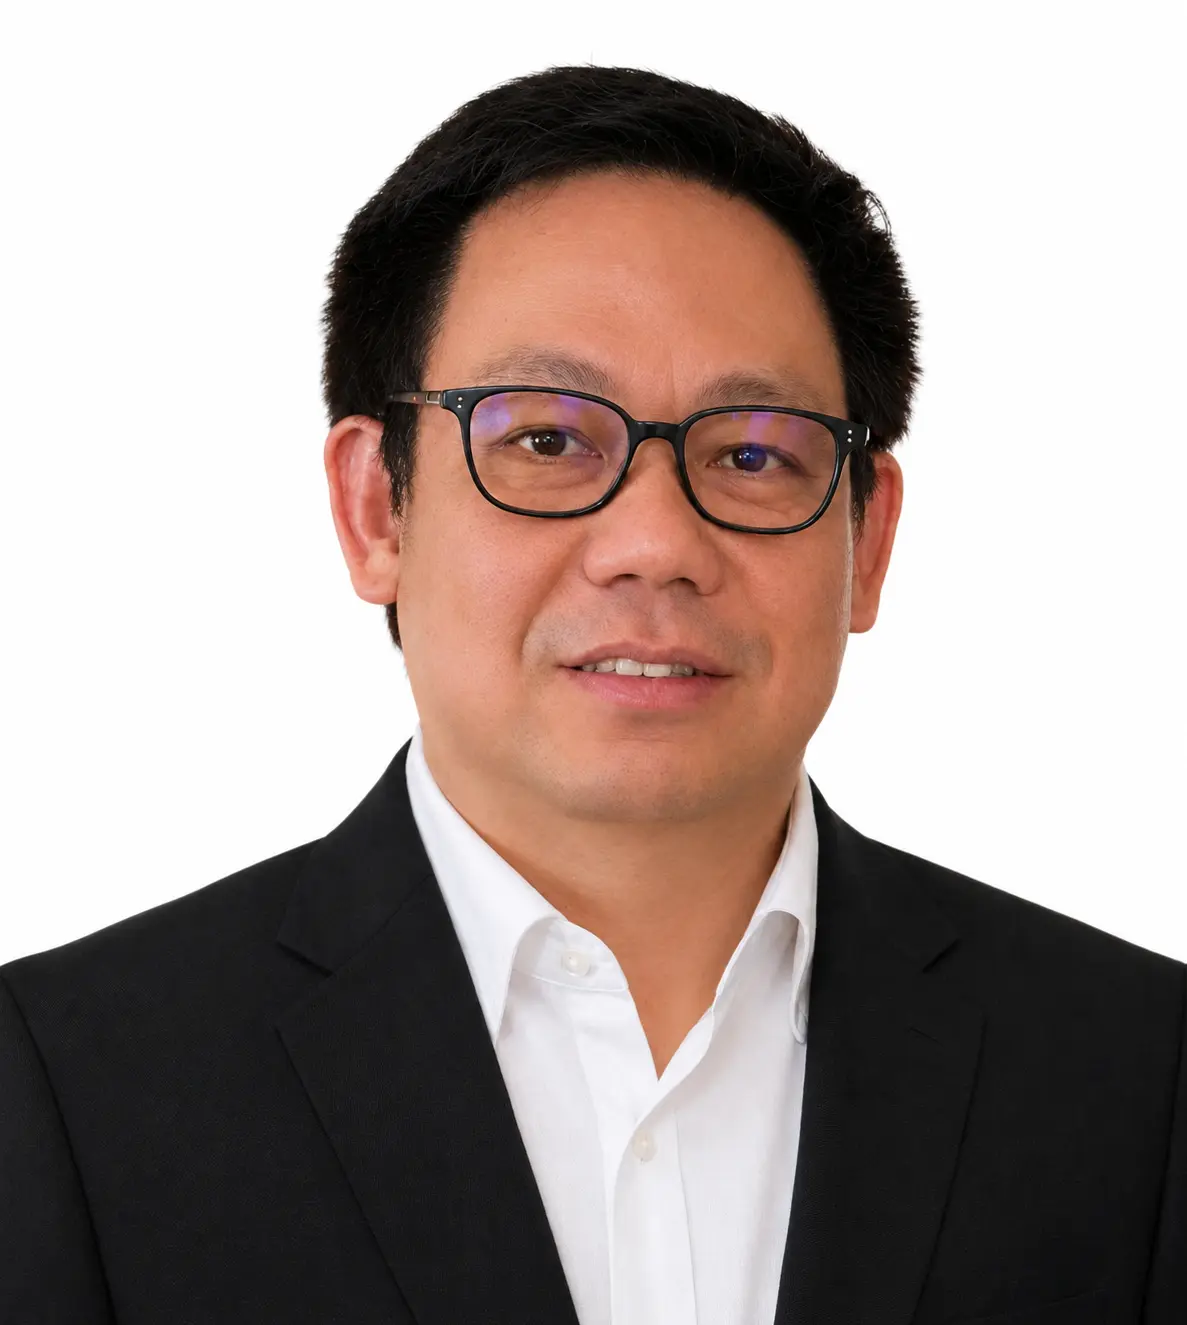
AI-enhanced portrait of Hendry Tamzel, real estate development advisor
HENDRY TAMZELREAL ESTATE DEVELOPMENT & ADVISORYAI-enhanced portrait
Meet the advisor

Analytical perspective.
Business understanding.

Hendry Tamzel began his career as a marketing specialist in 1992. He later served as a Director of Ciputra Group, with experience across more than 20 real estate projects in Indonesia and international markets.

His work spans project initiation, development strategy, financial feasibility, risk assessment, business models, organizational design, and strategic marketing. Today, Hendry also shares his experience as an educator, consultant, and business-to-business liaison.

30+years in real estate
20+projects across markets
1992career began
Hendry TamzelHENTZ · Strategic Real Estate Advisory
Hendry Tamzel · Selected experience

A perspective shaped by real projects.

Hendry’s career as a developer and strategic consultant includes residential, commercial, and township developments. His role and scope of involvement vary by project.
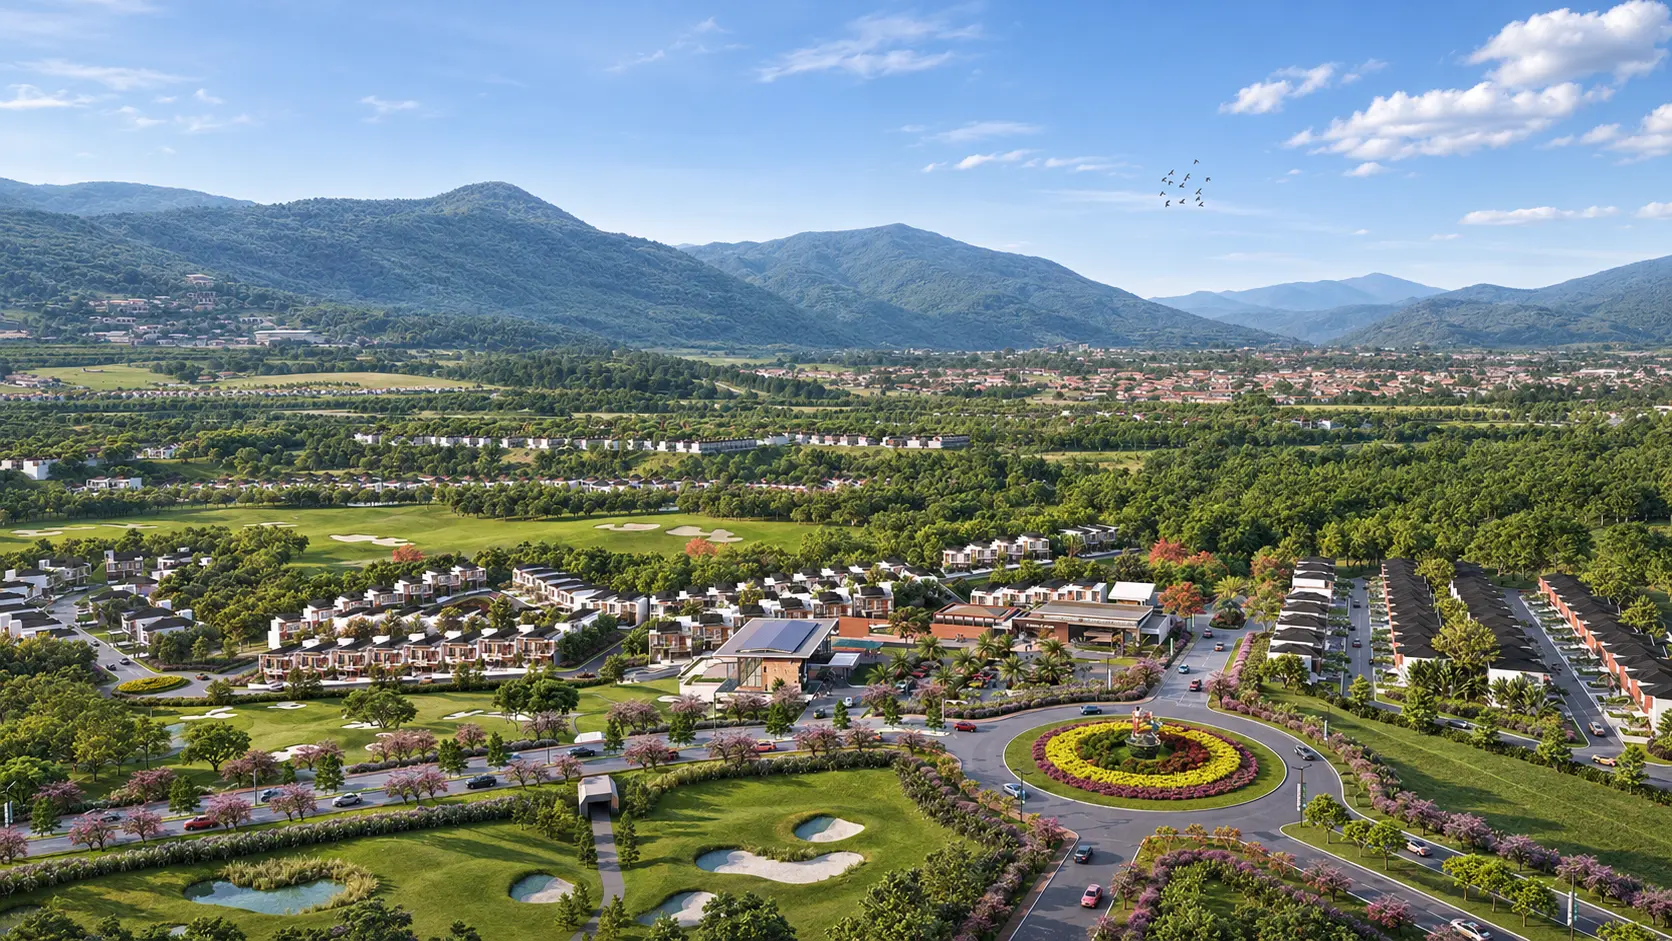
AI-enhanced visualization of Citra City Sentul and its surrounding landscape
Township · Sentul, West Java

Citra City Sentul

An integrated development in Sentul that brings together urban living and a green landscape.

AI-enhanced project visualization
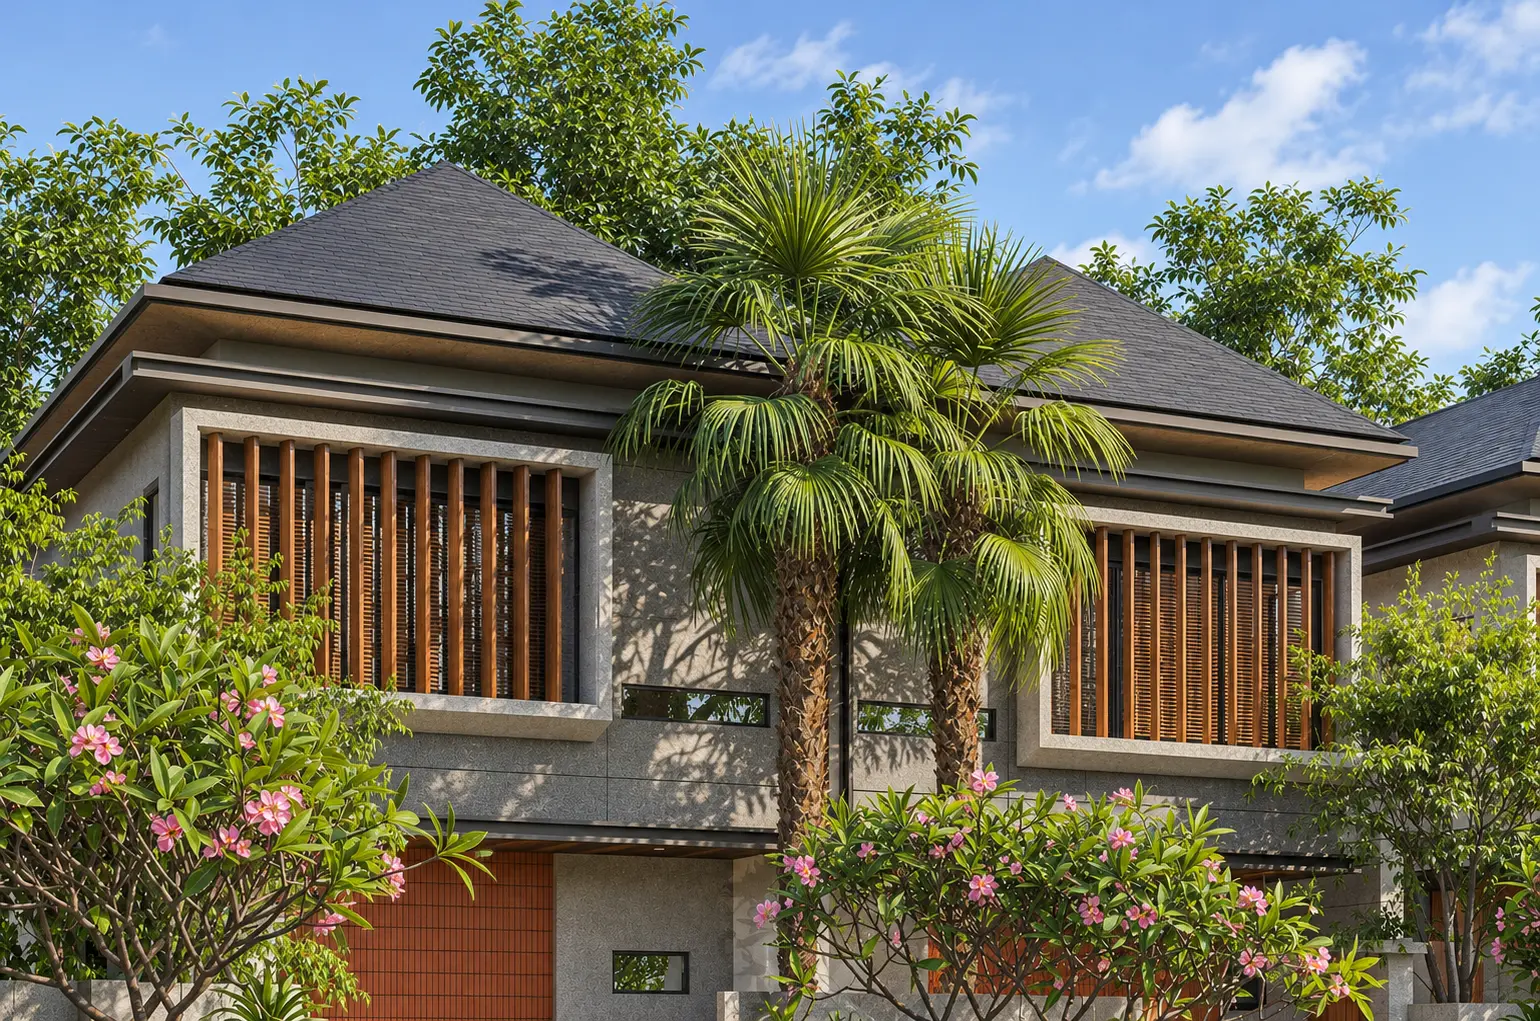
AI-enhanced visualization of tropical architecture at Bale Dame in Sanur, Bali
Residential · Sanur, Bali

Bale Dame

A contemporary tropical residential development in the Sanur area of Bali.

AI-enhanced project visualization

Additional experience

A wider portfolio across markets.

Grand Phnom Penh, CambodiaCitra Garden City, JakartaCitra Grand City, PalembangCitra Tower, KemayoranCitra BMW, CilegonSentul CityJonggol Agro EstateThe Spring of Pakuan
Start a conversation

Let’s talk about your next decision.

Every project has its own context. Tell us about the challenge or opportunity you are facing to start a conversation with HENTZ.

For developers, investors, and real estate companies in Indonesia.
WhatsApp+62 811 828 385

Prepare your message

Share a few details, then continue the conversation on WhatsApp.

Continue to WhatsApp

WhatsApp will open with your message ready to review and send.

AI-enhanced portrait of Hendry Tamzel
HENTZ · Advisor profile

Hendry Tamzel

Real Estate Development & Strategic Advisory

With 34 years of experience in the real estate industry, Hendry Tamzel brings an extensive understanding of property development, corporate strategy, and large-scale project management.

Beginning his career in 1992, Hendry evolved from a marketing specialist into a multidisciplinary real estate executive, ultimately serving as Director of Ciputra Group, one of Indonesia's leading property development companies.

Throughout his career, he has overseen more than 20 real estate projects across Indonesia and international markets, developing a comprehensive perspective on the commercial, financial, organizational, and operational dimensions of property development.

His expertise extends well beyond marketing. Hendry specializes in real estate project initiation and strategic development planning, integrating market opportunities with financial feasibility, project risk assessment, business model development, organizational design, and implementation-oriented marketing strategies.

He believes that successful real estate development begins with sound fundamentals, strategic clarity, and the ability to translate business plans into measurable results.

His approach emphasizes the relationship between planning, design, financial performance, and market positioning—ensuring that development concepts are not only attractive but also commercially viable and operationally executable.

Today, Hendry is actively engaged as an educator, real estate development consultant, and strategic business liaison. In addition to sharing his expertise with the next generation of property professionals, he facilitates business-to-business collaborations between international companies and major Indonesian real estate developers, helping foreign enterprises explore strategic partnerships and market-entry opportunities.

Areas of Expertise

Bridging strategic vision, commercial feasibility, and real-world execution.

Illustrative city skyline and waterfront
Illustrative image
Real estate strategy

Why Property Developers Need Operations Research

A property project can have an attractive site, a compelling design and a strong sales team—and still struggle because the decisions behind them do not work together.

Land, product, capital, price and timing are often discussed separately. In reality, a decision in one area changes what is possible in the others. A denser masterplan can increase potential revenue, but it may also require more infrastructure, more upfront cash and a longer sales period. A lower entry price may attract buyers, but could leave too little margin to deliver the promised environment.

Operations Research (OR) helps decision-makers examine these relationships. It uses data and analytical models to compare choices under real constraints. Its purpose is to make business judgment more informed—not to pretend that the future can be predicted with certainty.

The most saleable land is not always the most valuable land

Consider a developer deciding how to use a site. Maximizing the number of units may look attractive when measured by gross development value. But more units can bring higher costs for access, drainage, utilities or shared facilities. They can also compete for the same pool of buyers over a longer period.

A different way to compare two concepts

Assume two hypothetical concepts on the same site. Both figures below are before tax and financing, and assume all units sell at the stated average price.

  • Concept A: 200 homes at Rp 1.5 billion each produce Rp 300 billion in projected revenue. At Rp 252 billion in total project costs, the projected surplus is Rp 48 billion.
  • Concept B: 160 homes at Rp 1.65 billion each produce Rp 264 billion in projected revenue. At Rp 200 billion in total project costs, the projected surplus is Rp 64 billion.

Concept A creates more units and higher revenue; Concept B produces a higher surplus under these assumptions. The next question is whether the market will buy each product at that price and pace—and whether the developer can fund its delivery.

Illustrative assumptions only. The comparison excludes financing, tax, timing, risk and any value of unused land; it is not a project forecast.

Where connected decisions make the difference

Optimization begins with the right question

A useful model starts with a business objective and the limits that cannot be ignored. Depending on the project, the objective might be to improve risk-adjusted value, use capital more efficiently or find a feasible mix of products. Constraints can include available cash, land area, infrastructure capacity, delivery commitments and realistic demand.

The result is not one magical number. It is a clearer view of trade-offs: which option requires more funding, which assumption has the greatest effect on feasibility, and where a decision becomes difficult to execute. Scenario analysis can then explore how those choices perform if sales slow, costs rise or a key milestone moves.

Better questions create better projects

For Indonesian developers, market comparisons should reflect the actual locations and buyers being served: competing products, dimensions, specifications, pricing, payment schemes and the quality of the surrounding environment. National indicators add context, but they do not replace evidence from the project’s own market.

Models are only as useful as their assumptions. Historical sales may not repeat, buyer preferences change, and incomplete costs create false confidence. The strongest decisions combine analytical discipline with local market knowledge, design judgment and an honest understanding of uncertainty.

Illustrative financial charts and laptop on a desk
Illustrative image
Investment decisions

The Science of Real Estate Investment Decisions

A project can promise an attractive return and still be the wrong investment for the company considering it. The missing question is often: what must happen—and how much cash must be available—before that return can be achieved?

Real estate investment decisions are shaped by more than the final profit in a feasibility study. The timing of land payments, construction spending, collections and financing can change both the return and the risk. Two projects with similar forecast profits may demand very different amounts of capital and management attention.

The same profit can produce very different returns

Time changes the comparison

Assume each opportunity requires Rp 100 billion today and returns a single Rp 130 billion payment at the end of its term, including the original capital.

  • Project A: Rp 130 billion is returned after two years. The total gain is 30%, equivalent to approximately 14.0% per year when compounded annually.
  • Project B: The same Rp 130 billion is returned after four years. The total gain is still 30%, but the equivalent annualized return is approximately 6.8%.

Illustrative amounts only. This simplified comparison assumes no intermediate cash flows, debt, fees or tax and does not assess differences in risk. Actual project cash flows are usually more complex.

Timing is only one part of the decision. A faster project can carry greater risk, require more capital at its peak or offer less reliable demand. The point is to understand what sits behind a percentage before comparing it with another opportunity.

Distinguish value, project return and equity return

Return metrics such as margin, net present value and internal rate of return answer different questions. None should be read alone: an appealing percentage can sit alongside a funding gap that the company cannot cover.

Profit is not the same as available cash

A presale or signed agreement is a commercial milestone, but cash may arrive later. For residential projects, the timing can depend on customer payment terms, mortgage approval and the conditions attached to bank disbursements. At the same time, land instalments, infrastructure and contractors may require payment.

A decision-ready investment view therefore considers the lowest forecast cash balance, the peak funding requirement, financing terms and the amount needed to complete existing commitments. Cash held in another entity or restricted account should not be assumed available without checking the relevant conditions.

Look at the downside before comparing the upside

Scenario analysis is valuable because it makes assumptions visible. It does not assign certainty to a forecast. A project’s resilience depends on the credibility of its market evidence, the flexibility of its commitments and the actual capacity of its investors.

The best investment must fit the investor

A high-return opportunity that consumes all available liquidity may prevent a developer from completing another promising project. A lower-return opportunity with manageable funding needs can sometimes strengthen the overall portfolio. The right decision depends on capital, obligations, risk tolerance and strategic objectives—not on a single headline number.

Illustrative city skyline with modern commercial buildings
Illustrative image
Commercial performance

Optimizing Property Sales Performance

More leads do not automatically mean more sales. A full database can hide a weak product-market fit, slow follow-up or an offer that attracts attention from people who are unlikely to buy.

Sales performance is shaped long before an advertisement appears. Location, target buyer, product design, price, payment scheme, inventory release and the sales experience all influence the path from interest to transaction. Optimization means improving the relationship between these factors—not simply increasing promotional activity.

The cheapest lead can be the more expensive sale

Two campaigns, one important difference

Assume each campaign spends Rp 50 million and bookings are attributed to the same measured cohort and observation period.

  • Campaign A: 1,000 leads and 10 bookings. The advertising cost is Rp 50,000 per lead and Rp 5 million per attributed booking.
  • Campaign B: 250 leads and 12 bookings. The advertising cost is Rp 200,000 per lead and approximately Rp 4.17 million per attributed booking.

Campaign B has a higher cost per lead but a lower advertising cost per attributed booking in this example. The conclusion could change after cancellations, collection, unit margin and other sales costs are included.

Illustrative data only. Attribution does not prove that a campaign caused each booking; compare consistent cohorts over a sufficiently long period and account for the different buyers and units involved.

Diagnose where buyers are leaving

A useful commercial view follows a cohort beyond the first enquiry. Definitions should be consistent across the in-house team, agents, events and digital channels.

A drop at each point calls for a different response. A team that only measures lead volume can spend more money filling the top of the funnel while the real problem remains further down.

When the problem is the product, more promotion is costly

A project may receive interest yet struggle to convert because the product is positioned between buyer segments: too expensive for one group and missing the features expected by another. The answer may lie in layout, unit dimensions, specifications, access, facilities or the credibility of the surrounding environment.

Compare the project with relevant competitors from the buyer’s perspective—not just on price per square metre, but on what the buyer receives and the payment required. Sales-team feedback and lost-deal reasons can reveal recurring objections worth investigating, though a few anecdotes are not proof of market-wide demand.

Price, incentives and inventory must work together

Build a sales system that learns

Useful reporting connects market intelligence, campaign source, sales activity and actual commercial outcomes. Compare like-for-like periods and cohorts, account for the time between enquiry and purchase, and record both successful and lost opportunities. Digital attribution can inform a decision, but property purchases often involve several online and offline touchpoints.

The objective is not merely a higher conversion rate. It is a healthier combination of buyer fit, sales pace, realized margin and cash collection—supported by a product the market values and a team that can deliver what was promised.

Illustrative image of development plans and a financial analysis overlooking a city
Illustrative image
Real estate strategy · Cash flow

When Sales Slow: Protecting Cash Flow and Project Value

A project can look profitable on paper and still run short of cash. In real estate development, the critical question is not only how much value a project may create, but whether money arrives in time to meet its commitments.

When sales slow, the effect travels beyond the marketing department. Customer collections may be delayed while land payments, construction certificates, infrastructure, operating costs and financing obligations continue. A sound response connects the sales plan to the construction programme and to capital that is actually available.

Why the distinction matters in Indonesia

Payment schedules differ between cash purchases, developer instalments and bank mortgages (KPR). A booking or sales agreement is not the same as money in the project account; bank approval, payment milestones and the terms of the transaction can affect when funds are released.

In Bank Indonesia’s Q2 2026 residential property survey, developer internal funds accounted for 73.28% of reported development financing, while bank housing loans accounted for 70.05% of purchase schemes. These survey figures describe the market sample, not the funding mix of every project.

Read the cash position behind the sales figure

Make the funding gap visible

Use a rolling monthly forecast, supported by a shorter-term weekly view when liquidity is tight. Link expected collections to payment schedules and compare them with the timing of obligations. Include financing receipts only when they can reasonably be drawn under the relevant facility conditions.

Closing available cash = opening available cash + cash received − cash paid

A simple illustration

Assume a single period with Rp 20 billion in opening available cash, Rp 26 billion in cash payments and a required minimum reserve of Rp 5 billion.

  • Base case: Rp 18 billion is collected. Closing cash is Rp 12 billion (20 + 18 − 26).
  • Slower sales: Only Rp 9 billion is collected. Closing cash is Rp 3 billion (20 + 9 − 26).
  • Decision implication: The slower case is Rp 2 billion below the reserve, before any additional financing or changes to spending.

Illustrative amounts only. This simplified example assumes all cash is usable and excludes other receipts, payments and financing; an actual project needs a period-by-period forecast.

Protect delivery while preserving flexibility

Optimization is the disciplined balancing of accessible capital, market absorption and delivery commitments. The strongest decision is the one that keeps the project viable under more than one plausible outcome.

Illustrative image of construction cost planning and a development site
Illustrative image
Real estate strategy · Cost resilience

When Construction Costs Rise: Protecting Project Feasibility

A project does not become unviable only when construction costs exceed the budget. It becomes vulnerable when higher costs change the relationship between product value, cash requirements and the return a developer can realistically achieve.

For an Indonesian developer, the question is not simply whether steel, concrete or labour is more expensive. It is how much of the project remains exposed, who bears the increase under the relevant agreements, and whether the revised development can still be funded and sold as planned.

Understand where the exposure sits

Revisit the whole feasibility picture

A headline percentage applied to every line can exaggerate the impact if some work has already been paid for or genuinely price-locked. Equally, looking only at the building contract can understate exposure to infrastructure, variations or longer financing periods.

A simple illustration

Assume projected sales revenue of Rp 200 billion and total project costs of Rp 160 billion, before tax and financing. Of that cost, Rp 80 billion remains exposed to repricing.

  • Base case: The projected surplus before tax and financing is Rp 40 billion, or 20% of revenue.
  • Cost stress: If the exposed Rp 80 billion increases by 10% and the developer bears the full increase, costs rise by Rp 8 billion to Rp 168 billion.
  • Decision implication: With revenue unchanged, the surplus falls to Rp 32 billion, or 16% of revenue. The cash impact depends on when the extra Rp 8 billion must be paid.

Illustrative amounts only. This example assumes no change in sales, contingency or schedule and excludes tax and financing; it is not a project forecast.

Protect value, not just the budget

Optimization means choosing the combination of cost, quality, timing and capital that protects the project’s commercial proposition. The least expensive design is not automatically the most valuable one.

Illustrative image of a construction site viewed from a project office on a rainy day
Illustrative image
Real estate strategy · Delivery & timing

When Construction Is Delayed: Understanding the Financial Consequences

Time is a financial variable in property development. A delay can postpone collections or handovers while extending site overheads, financing obligations and the period during which capital is tied up.

Not every late activity delays a project’s completion. The strategic question is which milestones have actually moved, which commitments depend on them, and whether the project can absorb the new timing without undermining delivery or liquidity.

Look beyond the revised completion date

Translate time into the cost to complete

Compare the original and revised programme with the same cash-flow model. Rephase payments and receipts first, then add genuinely incremental costs; a payment moved to a later month is not necessarily an additional cost.

A simple illustration

Assume completion is delayed by three months. The developer carries Rp 40 billion in debt at a simple annual interest rate of 12%, with the balance unchanged during the delay. Incremental site overhead is Rp 0.2 billion per month.

  • Extra interest: Rp 40 billion × 12% × 3/12 = Rp 1.2 billion.
  • Extra site overhead: Rp 0.2 billion × 3 = Rp 0.6 billion.
  • Decision implication: The two specified incremental costs total Rp 1.8 billion, before any separate effect from shifted receipts, other costs or contractual recoveries.

Illustrative amounts only. Interest is simplified, with no compounding or principal repayment; the example assumes the developer bears both costs and is not a project forecast.

Compare practical responses

The objective is not to recover every lost day at any price. It is to select a realistic delivery plan that protects obligations, cash availability and the long-term value of the development.

Illustrative image of a development team reviewing project plans and financial scenarios
Illustrative image
Real estate strategy · Integrated risk

When Risks Converge: Making Decisions Under Multiple Pressures

A development can appear resilient to a single setback and still face a serious funding problem when several pressures arrive together. Sales, construction costs and timing all draw on the same project resources.

Slower sales can reduce near-term collections. Higher costs can increase the cash needed to complete the project. Delays can shift handovers and receipts into later periods while extending site and financing costs. Their combined effect must be understood as a connected business problem.

See the connections between risks

Move from separate stresses to a coherent scenario

A one-variable sensitivity test changes one assumption at a time to reveal its effect. A combined scenario brings several consistent assumptions into the same period-by-period forecast. Neither approach predicts the future; each helps a decision-maker understand exposure.

A simple illustration

For one period, assume opening available cash of Rp 20 billion, base collections of Rp 18 billion, base payments of Rp 26 billion and a required reserve of Rp 5 billion. Base closing cash is Rp 12 billion.

  • Separately: A Rp 6 billion reduction in collections leaves Rp 6 billion. A Rp 4 billion cost increase leaves Rp 8 billion. A delay that shifts Rp 3 billion of collections and adds Rp 1 billion of cost also leaves Rp 8 billion. Each remains above the reserve in isolation.
  • Together: Collections fall from Rp 18 billion to Rp 12 billion, then Rp 3 billion of the remaining collections moves to a later period. Payments rise from Rp 26 billion to Rp 31 billion, including the distinct Rp 4 billion increase and Rp 1 billion delay cost.
  • Decision implication: Before additional funding, the period closes at Rp −2 billion (20 + 9 − 31). The shortfall against the Rp 5 billion reserve is Rp 7 billion.

Illustrative amounts only. A negative closing figure represents an unfunded shortfall before financing, not an assumed negative bank balance. Later receipts and periods must also be modelled; the example is not a forecast.

Evaluate choices against capacity and risk tolerance

The aim of optimization is not to find the most attractive result under one forecast. It is to identify a development and funding strategy that can be executed within the organization’s actual capacity and risk tolerance across plausible outcomes.

Sources & further reading